Financial Planning for Young Professionals Starting Their Careers
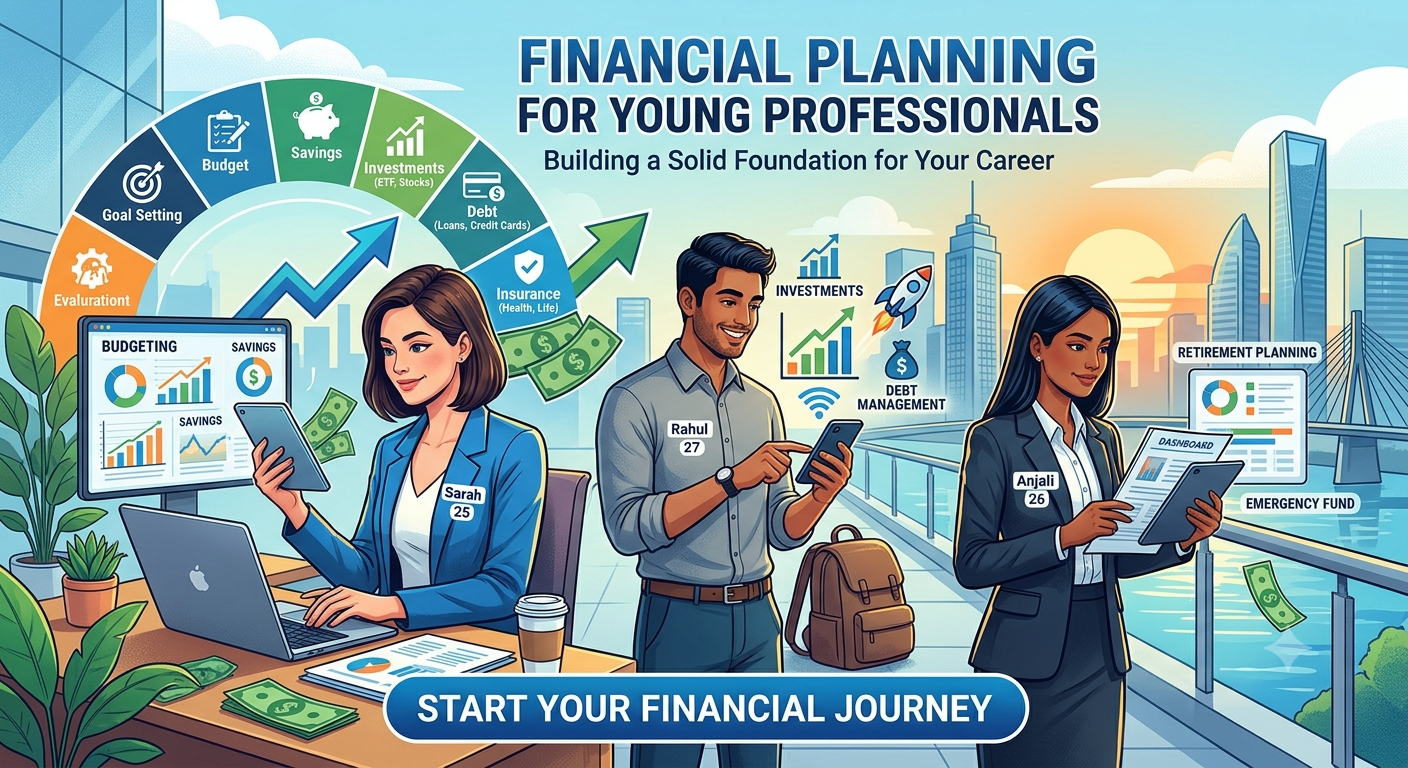
Starting a career is an exciting milestone. Along with new responsibilities and professional opportunities, young professionals begin making important financial decisions that can influence their future. Managing a first salary, paying regular expenses, building savings, and planning for long-term goals may feel challenging at first, especially when several financial priorities compete for attention.
The good news is that financial planning does not require a high income or complicated strategies. Developing practical money habits early can help young professionals become more financially independent and better prepared for unexpected expenses.
Whether you have recently started your first job or are still adjusting to a regular income, the following steps can help you build a stronger financial foundation. Understanding different financial options, including an instant short term personal loan, can also be useful, provided you evaluate borrowing carefully and understand the repayment responsibilities.
1. Understand Your Salary and Monthly Expenses
The first step towards financial independence is understanding how much money you receive and where it goes. Your salary may look sufficient initially, but rent, transportation, food, utilities, and other regular expenses can quickly reduce the amount available for savings.
Start by creating a simple monthly budget. Include:
-
Take-home salary after applicable deductions
-
Rent and household expenses
-
Food and groceries
-
Transportation and commuting costs
-
Mobile, internet, and utility bills
-
Education expenses or professional development
-
Existing financial commitments
-
Savings and discretionary spending
Track your spending for at least a month to understand your actual habits. This can help you identify unnecessary expenses and decide how much you can realistically save.
A budget should be practical rather than restrictive. Allow room for occasional entertainment and personal interests while ensuring that essential expenses and savings remain priorities.
2. Build an Emergency Fund Early
Unexpected expenses can arise at any stage of your career. Medical bills, urgent travel, household repairs, or a temporary gap between jobs can create financial pressure if you have no savings available.
An emergency fund provides a financial cushion for such situations. Start with a small, manageable contribution from each salary and increase it as your income grows.
Consider these habits:
-
Transfer money into savings soon after receiving your salary.
-
Keep emergency savings separate from everyday spending money.
-
Use the fund only for genuine, unexpected needs.
-
Replenish the amount after withdrawing money.
-
Gradually work towards covering several months of essential expenses.
Young professionals may have limited savings during their first few working years. That is normal. Consistent contributions are more important than trying to save a large amount immediately.
3. Develop a Healthy Savings Habit
Saving regularly can help you prepare for both short-term needs and long-term ambitions. These goals may include further education, buying a vehicle, moving to a new city, supporting family members, or eventually purchasing a home.
Instead of saving whatever remains at the end of the month, decide on a realistic savings amount when planning your budget.
You can divide savings into different categories:
Short-term goals: Expenses you expect to meet in the near future, such as a professional course or planned relocation.
Emergency savings: Money reserved for urgent and unforeseen requirements.
Long-term goals: Future priorities that may require several years of preparation.
Review your savings plan whenever your salary, living arrangements, or family responsibilities change. Even small contributions can become meaningful when maintained consistently.
4. Manage Lifestyle Inflation
Receiving your first salary or getting a promotion can create the temptation to increase spending. You might want a more expensive phone, frequent restaurant visits, new subscriptions, or a higher-cost lifestyle.
Enjoying your income is reasonable, but allowing every salary increase to become additional spending can make financial progress difficult.
Try increasing your savings whenever your income rises. Before making a significant purchase, consider whether it fits your budget and whether you genuinely need it.
You do not have to avoid every non-essential expense. The objective is to make deliberate choices rather than spending automatically because your income has increased.
5. Understand Credit and Borrowing Before You Need It
Young professionals may encounter credit cards, personal loans, and other borrowing options early in their careers. Understanding how these products work can help you avoid costly mistakes.
Before taking any form of credit, ask yourself whether the expense is necessary, whether you can manage it through savings, and whether the repayment will fit your monthly budget.
If you are considering an instant short term personal loan, review the complete terms before applying. The name does not guarantee instant approval or immediate disbursement. Processing times, eligibility requirements, documentation, and charges depend on the lender and the applicant's circumstances.
Pay attention to:
-
The applicable interest rate and total repayment obligation
-
Processing fees and other disclosed charges
-
Repayment dates and instalment amounts
-
Late-payment consequences
-
Prepayment or foreclosure conditions
-
The lender's identity and credibility
Borrow only when the need and repayment plan are clear. A short repayment period may result in larger instalments, so check affordability rather than focusing only on how quickly funds might be available.
6. Build a Responsible Credit History
Your credit history can become important when you apply for certain financial products. Although young professionals may have limited borrowing experience, they can still develop responsible financial habits from the beginning.
If you use a credit card or have an existing loan, pay on time and monitor your statements. Avoid spending more than you can repay and understand the consequences of carrying outstanding balances.
Useful habits include:
-
Paying bills and loan instalments by their due dates
-
Reviewing credit reports for errors
-
Keeping track of outstanding balances
-
Avoiding unnecessary loan and credit applications
-
Borrowing only when repayment is manageable
A good credit history does not guarantee approval for future borrowing. Lenders may consider several factors, including income, existing obligations, credit information, and their own eligibility requirements.
7. Invest in Skills That Can Increase Your Earning Potential
Financial planning is not only about controlling expenses. Increasing your earning potential can also improve your financial position over time.
Young professionals can explore courses, certifications, communication training, technical skills, or industry-specific knowledge that supports their career goals.
Before paying for a course, research its relevance, credibility, curriculum, and potential value in your chosen field. Consider whether you can learn through affordable resources or employer-supported training.
Set aside a reasonable amount for professional development when possible. Improving your skills can support career progression, but no course or certification guarantees a particular salary or job outcome.
8. Understand Insurance and Financial Protection
Many young professionals focus on salary and savings while overlooking financial protection. Depending on their circumstances, health insurance and other suitable forms of coverage may help reduce the financial impact of certain unexpected events.
Review any coverage available through your employer and understand its limitations. Check whether it continues if you change jobs and whether additional personal coverage may be appropriate for your situation.
Read the policy terms carefully, including exclusions, waiting periods, coverage limits, and claim requirements.
If you support family members financially, consider how a major illness or loss of income could affect their needs. Planning for these risks can help you make more informed decisions about financial protection.
9. Plan for Taxes and Salary Deductions
Your gross salary may differ from the amount credited to your bank account. Depending on your employment and circumstances, deductions may include tax and other applicable contributions.
Understand the components of your salary slip, including take-home pay, deductions, and any employment benefits. Keep relevant financial documents organised and review your tax obligations using current official guidance.
Do not make investment or tax decisions based only on social media claims. If your circumstances are complicated, consider obtaining guidance from a qualified professional.
A clear understanding of your take-home salary helps you prepare a realistic budget and avoid committing money that is not actually available for spending.
10. Set Financial Goals With Clear Timelines
Financial goals become easier to manage when they are specific and realistic. Rather than simply deciding to save more, identify what you want to achieve and when you hope to achieve it.
For example, you might want to build an emergency fund, pay for a professional qualification, reduce existing debt, or start investing for long-term needs.
For each goal, determine:
-
The purpose of the goal
-
The approximate amount required
-
Your intended timeline
-
How much you can contribute regularly
-
What adjustments may be necessary if your circumstances change
Review your progress every few months. Goals may need to change as your salary, responsibilities, and priorities evolve.
11. Avoid Comparing Your Financial Journey With Others
Young professionals often compare their salaries, purchases, travel, and lifestyles with those of friends or colleagues. However, people may have different family responsibilities, financial support, debts, and living costs.
Trying to match someone else's lifestyle can encourage unnecessary spending or borrowing.
Focus instead on your own financial progress. Building savings, managing debt responsibly, improving your skills, and meeting your personal goals are more useful measures of progress than comparing purchases or income with others.
Make decisions according to your financial circumstances and priorities.
12. Review Your Financial Plan Regularly
A financial plan should evolve with your career. A budget that works during your first job may need to change after a promotion, relocation, marriage, or change in family responsibilities.
Set aside time each month to review your income, spending, savings, and outstanding commitments.
Ask yourself:
-
Am I saving consistently?
-
Are my essential expenses manageable?
-
Do I have enough money set aside for emergencies?
-
Have my financial goals changed?
-
Can I afford my existing debt repayments?
-
Are there expenses I should adjust?
Regular reviews help you identify issues early and make changes before they become difficult to manage.
Final Thoughts
Financial planning during the early years of a career is about developing habits that can support future stability. Understanding your salary, budgeting carefully, saving regularly, improving your skills, and managing credit responsibly can help you make better financial decisions as your responsibilities grow.
Borrowing may sometimes be appropriate for a necessary expense, but it should be approached carefully. If you explore an instant short term personal loan, compare the terms, understand the total cost, and ensure the repayment schedule fits your budget before proceeding.
A realistic financial plan does not need to be perfect. Consistent progress, informed choices, and regular reviews can help young professionals build a more secure financial future.
Frequently Asked Questions
1. What should young professionals do with their first salary?
Start by understanding your take-home salary, covering essential expenses, building emergency savings, and setting realistic financial goals. Leave room for discretionary spending while keeping savings a regular priority.
2. How can young professionals start saving with a limited salary?
Track expenses, set a manageable savings target, and transfer money into savings regularly. Review non-essential spending and gradually increase savings as your income improves.
3. Is an instant short term personal loan suitable for young professionals?
It depends on the purpose of borrowing, eligibility, overall cost, and ability to repay. Compare the terms carefully and avoid borrowing if repayments would make essential expenses difficult to manage.
4. Why is an emergency fund important at the start of a career?
An emergency fund can help cover urgent expenses or temporary income disruptions without immediately relying on credit. It can provide greater financial flexibility while savings are still developing.
5. How can young professionals build a responsible credit history?
Pay existing credit obligations on time, monitor credit reports, avoid unnecessary applications, and keep borrowing within a manageable level. Responsible repayment habits can support financial management over time.

 English
 Arabic
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek